<img src="//bat.bing.com/action/0?ti=5104607&amp;Ver=2" height="0" width="0" style="display:none; visibility: hidden;">

Advisors & Issuers

image 65

For over 40 years, The Entrust Group has empowered investors to take control of their retirement portfolios with self-directed IRAs. Now, we’re ready to invest in your career. Whether you’re a financial advisor, investment issuer, or other financial professional, explore how SDIRAs can become a powerful asset to grow your business and achieve your professional goals.

Learning Center

Learning-Center-menu-image-1

Access the largest knowledge base for Self-Directed IRAs. Expand your investor knowledge with articles, whitepapers, practical guides and tons of other educational resources.

About Entrust

teg-symbol-about-entrust-menu-image

For over 40 years, The Entrust Group has provided account administration services for self-directed retirement and tax-advantaged plans. Entrust can assist you in purchasing alternative investments with your retirement funds, and administer the buying and selling of assets that are typically unavailable through banks and brokerage firms.

solo-hero

How Your Small Business Can Supercharge Your Retirement Portfolio
solo-hero

If you're self-employed and contributing to a traditional or Roth IRA, you're capped at $8,600 in contributions this year.

Opening a solo 401(k) can unlock up to $83,250 in additional tax-advantaged, wealth-building potential.

And with an Entrust solo 401(k), you gain total control of your portfolio: how you're taxed, what you invest in, and when you can access your funds.

Get Started Talk to a Specialist

What Is a Solo 401(k)?

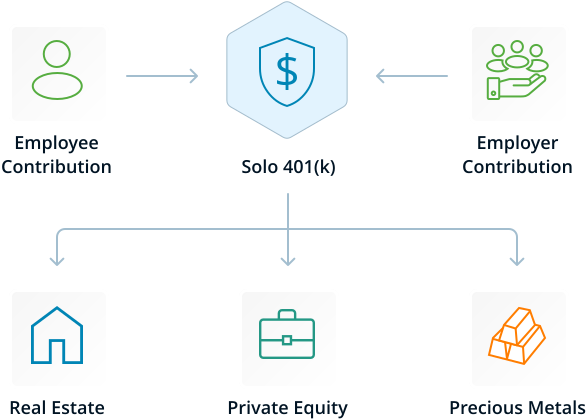
solo-graph

What Is a Solo 401(k)?

A solo 401(k) is a retirement plan built for self-employed individuals and small business owners with no full-time employees other than themselves, a spouse, or a business partner.

It lets you contribute as both employer and employee, unlocking the highest contribution limits of any retirement plan while giving you the freedom to invest in real estate, private equity, precious metals, and more.


The Benefits of a Solo 401(k)

Higher Contribution Limits.

Up to $72,000 in 2026 (or $83,250 with catch-up).

Borrow From Your Own Plan

Up to $50,000, tax-and penalty-free. Pay the interest back to yourself, not a bank.

ROTH

Pre-Tax or Roth, Automatically

Every Entrust solo 401(k) includes both from day one.


Leveraged Real Estate Advantage

Unlike an IRA, a solo 401(k) is exempt from UDFI on leveraged real estate (loans must be non-recourse).

Invest Beyond the Stock Market

Invest in any alternative asset the IRS allows:

Real Estate: Rental properties, commercial real estate, raw land, fix-and-flip projects

Private Lending & Mortgage Notes: Act as the bank and earn interest income
Private Equity & Startups: Invest in early-stage companies, venture funds, or private placements

Tax Liens & Deeds: Acquire government-backed liens on real property


Precious Metals: Gold, silver, platinum, and palladium

Why Open an Entrust Solo 401(k)?

45+ Years of Self-Directed Retirement Expertise

Decades of specialized experience in self-directed retirement accounts.

Best-in-Class Client Services Team

An in-house client services team based in Oakland, CA that knows solo 401(k)s inside and out.

We Handle the Paperwork
Transactions, recordkeeping, and the compliance infrastructure to help you stay on the right side of the IRS rules—handled for you, not by you.

Google Reviews

4.4 Stars | 176 reviews

See What Our Clients Have to Say

Solo 401(k) vs. SEP IRA

Compared to a SEP IRA, an Entrust solo 401(k) unlocks enhanced control and flexibility:
Feature
Solo 401 (k)
SEP IRA

Who Can Contribute

Employee + Employer

Employer only

Maximum Standard Contribution (2026)

$72,000

$72,000

Catch-Up Contribution (2026)

$11,250 for those aged 60-63;
$8,000 for those aged 50-59 and 64+ 

Not available

Pre-Tax and Roth?

Automatic

Pre-tax only

Loan Provision

Yes (up to $50,000)

No

Eligible Businesses

Owner-only (no full-time employees)

Any size

Open Your Solo 401(k) in 3 Steps

solo-401k-steps

Confirm You Qualify:

You must have self-employment income and no full-time employees beyond yourself, a spouse, or a business partner.

solo-401k-steps2

Get Your EIN:

Free, in minutes, via the  IRS.

solo-401k-steps3

Open Your Plan:

We prepare your plan documents, and you're ready to invest.

Know the Rules


Solo 401(k)s come with real IRS requirements: prohibited transactions, UBIT considerations, and annual reporting, to name a few.
See our full Solo 401(k) Rules guide.


readytoTakeControlofYourRetirement-updated

Ready to Take Control of Your Retirement?

Now you know what a solo 401(k) can do: higher contribution limits, real investment flexibility, and a provider that handles the heavy lifting so you don't have to.

The only thing left is to get started.

Get Started Talk to a Specialist

Frequently Asked Questions

Can I have a solo 401(k) if I also have a W-2 job?
Yes. You can maintain a solo 401(k) for your self-employment income even if you also participate in a 401(k) from another business. However, your total employee contributions across both plans cannot exceed the annual IRS limit.
What happens to my solo 401(k) if I hire employees?
If you hire a full-time employee (other than your spouse) who meets eligibility requirements, your plan loses its solo 401(k) status. You would need to either terminate the plan or convert it to a regular 401(k) plan that covers eligible employees.
Can I invest my solo 401(k) in real estate?
Yes. With a self-directed solo 401(k), you can purchase real estate, including rental properties, commercial buildings, raw land, and mortgage notes, as long as you follow IRS rules and avoid prohibited transactions.
Can I convert my solo 401(k) to a Roth?
Yes. You can convert pre-tax funds in your solo 401(k) to Roth by paying income tax on the converted amount in the year of conversion.
When do required minimum distributions (RMDs) begin for a solo 401(k)?  
RMDs from a traditional solo 401(k) begin at retirement age under current law (per SECURE 2.0). Roth solo 401(k) accounts are no longer subject to RMDs during the owner's lifetime.